A current ratio between 1.5 and 2 is a common guide for most industries. Business Queensland, a state government service, uses this range as its target (Business Queensland). It means you hold $1.50 to $2.00 of current assets for every $1.00 of liabilities due in the next 12 months. A ratio below 1.0 means short-term debts exceed short-term assets, which is a warning sign. A very high ratio can mean cash, stock or debtors are tied up. This is a rule of thumb, not an official Australian benchmark. The right level depends on your industry and how quickly cash moves through your business.
Last checked: 11 October 2026.
Current ratio = current assets ÷ current liabilities
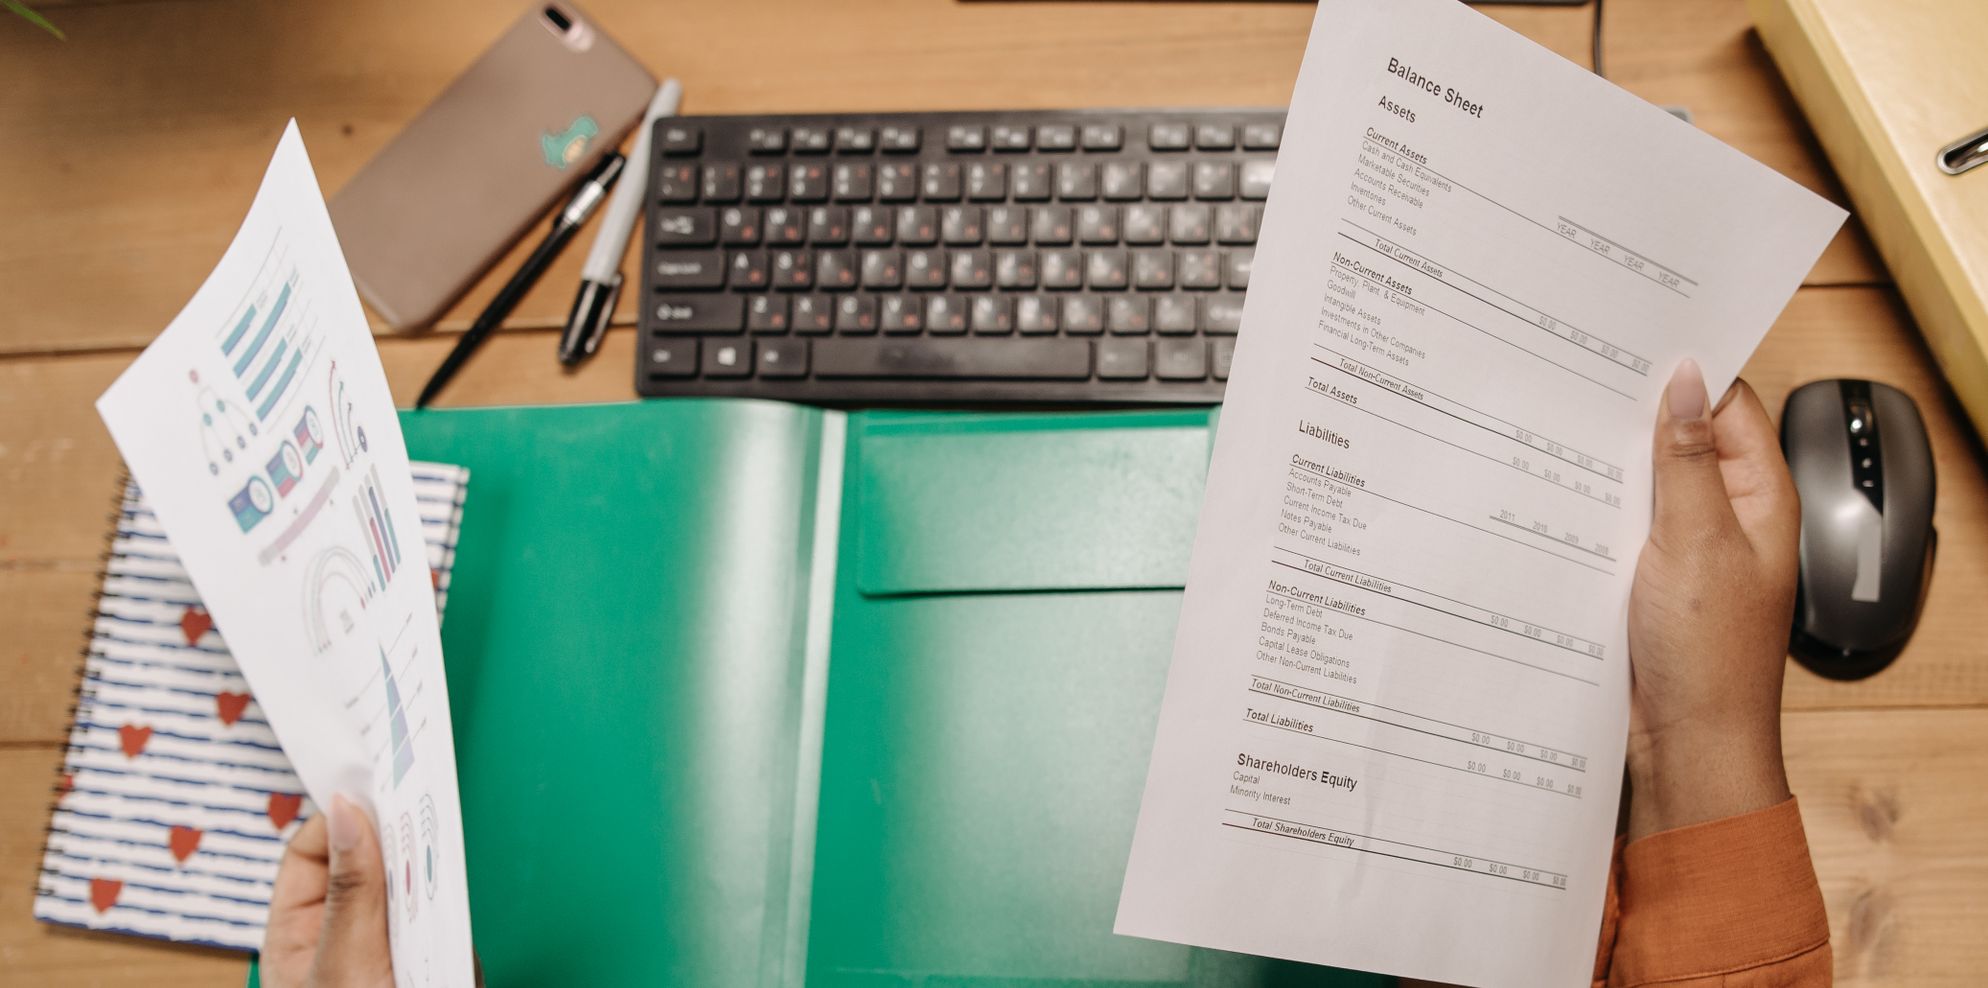
Both come from your balance sheet. See how to read a balance sheet.
Assumption: a $3 million revenue services business at 31 December, with no stock.
Current ratio = $630,000 ÷ $400,000 = 1.58
That is in the commonly cited range. But two thirds of current assets are receivables. If customers pay slowly, the ratio can look fine while the bank balance does not.
Working capital = current assets − current liabilities
Using the example above: $630,000 − $400,000 = $230,000. The ratio tells you the proportion. Working capital tells you the size of the buffer. A ratio of 1.58 means something different for a business with $40,000 of current liabilities than for one with $4 million.
Cash ratio = cash ÷ current liabilities
Using the example: $180,000 ÷ $400,000 = 0.45. The business could pay 45% of its current liabilities from cash today. Few businesses need a cash ratio of 1.0, but tracking it monthly shows whether liquidity depends on customers paying on time.
There is no official Australian industry dataset for current ratios that we are aware of, so treat these as general patterns:
Assumptions: a homewares retailer at 31 December with cash of $60,000, receivables of $10,000 and stock of $390,000. Current liabilities are $250,000.
The current ratio looks comfortable, but the business can pay only 28% of its short-term debts without selling stock. For a retailer, stock turnover and the age of the stock matter as much as the ratio itself.
The ratio is only as good as the balance sheet behind it. Common problems:
Assumptions: the equipment loan in the example has a total balance of $200,000, of which $40,000 is due within 12 months. At balance date the business has breached a loan covenant, and the lender can demand repayment.
Under AASB 101, a liability is current if the entity does not have the right at the reporting date to defer settlement for at least 12 months. A covenant breach that lets the lender demand repayment can remove that right.
The business is no different in cash terms, but the ratio falls from 1.58 to 1.13. Read loan covenants before year end, and talk to the lender early if a breach is likely.
Business Queensland defines the quick (acid-test) ratio as (current assets − inventory) ÷ current liabilities, with a guide of 1.0 or more. A stricter version also excludes prepayments: (cash + receivables) ÷ current liabilities.
Using the example above:
Assumptions: using the example above, the business takes out a $60,000 three-year term loan to pay overdue supplier invoices. $20,000 of the new loan is due within 12 months.
The ratio improves because $40,000 of the debt moved beyond 12 months. Interest is the cost. Get lending advice first.
Debtor days for the business above: $420,000 ÷ $3,000,000 × 365 = about 51 days. Reducing this to 40 days would bring receivables down to about $3,000,000 × 40 ÷ 365 = $328,767, releasing about $91,233 in cash. The current ratio stays similar, because cash replaces receivables, but liquidity improves.
The ratio is a snapshot of one day. It can move a lot with timing:
This is why lenders often look at the trend over several months rather than one balance sheet.
Under section 95A of the Corporations Act 2001, a person is solvent if they are able to pay all their debts as and when they become due and payable. That is a cash-flow test. A current ratio above 1.0 does not prove a company is solvent, and a ratio below 1.0 does not prove it is insolvent. What matters is whether cash will be there when each debt is due.
Directors have a duty to prevent insolvent trading (section 588G). If the ratio is falling and creditors are stretching, prepare a 13-week cashflow forecast and get advice early.
Track the current ratio monthly alongside cash runway, debtor and creditor days, gross margin and debt to equity. See key financial KPIs for Australian SMEs, the balance sheet health score and working capital for SMEs.
What is a good current ratio for a small business?
Between 1.5 and 2 is a common guide for most industries (Business Queensland). Read it with debtor days and cash.
Is a current ratio below 1 bad?
It is a warning sign. It means short-term liabilities exceed short-term assets.
What is the difference between the current ratio and the quick ratio?
The quick ratio excludes inventory (and, in stricter versions, prepayments), so it tests whether you can pay short-term bills without selling stock.
How often should I check it?
Monthly, after the books are reconciled.
What is the difference between the current ratio and working capital?
The current ratio divides current assets by current liabilities. Working capital subtracts them, giving the buffer in dollars.
Does a lender use the same current ratio as me?
Not always. Lenders may adjust the balance sheet, for example by excluding related-party loans or old stock, and some loan agreements define their own working capital ratio. Check the definition in your facility agreement.
Can a business with a current ratio above 1 be insolvent?
Yes. Solvency depends on whether the business can pay its debts as and when they fall due. A ratio built on slow debtors or old stock can sit above 1.0 while the bank account runs dry.
Scale Suite keeps SME balance sheets reconciled monthly and reports these ratios to owners and boards. Visit Scale Suite | Finance services | Board and investor reporting
General information only, current as at October 2026. Scale Suite is a registered BAS Agent, not a licensed financial adviser.
Scale Suite is a Sydney-based provider of outsourced finance and HR services for Australian SMEs. We deliver bookkeeping, financial reporting, payroll processing, fractional CFO support, recruitment, employee onboarding, people and culture support, and fractional HR oversight, all as a fully embedded team that works inside your business.
Employment Hero Gold Partner, CA-qualified, and Xero Certified, we replace fragmented finance and HR processes with one responsive, senior-level function at a fraction of the cost of full-time hires. We serve growing businesses across Sydney, Melbourne, Brisbane, Adelaide, and Perth, with packages starting from $1,500 per month and no lock-in contracts.
30 minutes with our team.
We will review your current finance setup, compare the full cost of an internal hire against our embedded team, and show you exactly what your finance function should cost at your stage of growth.
You will leave with a clear view of what is working, what is missing and where you would save.
No lock-in contracts. 30-day money-back guarantee.
Prefer to book directly? Grab a time here.